 1 week ago
20
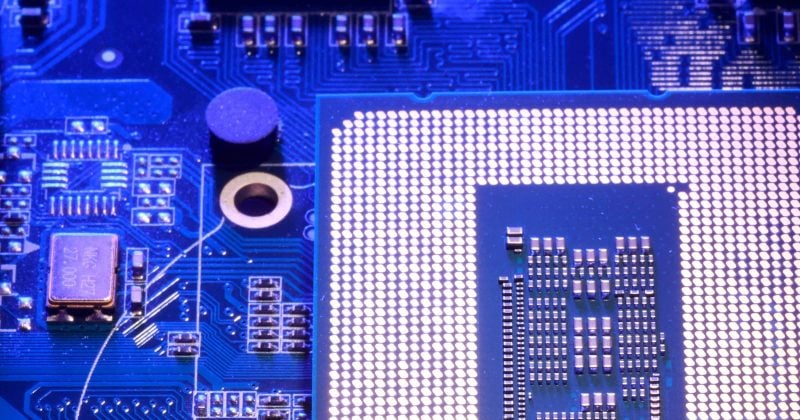
JPMorgan just handed SK Hynix one of the more bullish initiations in the semiconductor space this year, slapping an Overweight rating and a $245 price target on the memory giant. The target is set for June 2027, and the thesis boils down to one word: AI. The bank’s analysts project a 34% compound annual growth rate in earnings per share over the next two years, fueled by what they describe as an AI-driven memory upcycle that could stretch beyond five years. For a company already posting gross margins around 76%, that kind of earnings trajectory makes the current valuation look, well, modest. The numbers behind the conviction SK Hynix currently trades at a price-to-earnings multiple of roughly 7.1x. JPMorgan’s $245 target implies approximately a 20% premium over SK Hynix’s native share price when translated through its American Depositary Receipt listing. The target works out to about 7x average EPS for fiscal years 2026 and 2027. Memory average selling prices are forecasted to climb from Q1 2024 through at least Q4 2028. That’s a four-plus year pricing tailwind. Why AI changes the memory math JPMorgan’s research highlights an expectation that memory content per AI system will incre...
Related
South Korean President Lee Jae Myung faces pressure from Tru...
41 minutes ago
0

US approves $24B sale of F-35 fighter jets to Saudi Arabia
44 minutes ago
0
Indian government recruits overseas Indians to bolster rupee...
53 minutes ago
0
Popular






The CLARITY Act won’t move markets. It will move people.
1 month ago
38

 English (US) ·
© Clint's Cryto News 2026. All rights are reserved
